
By Jude Anderson September 26, 2026
Debit card surcharge rules do not change because a customer selects “credit” at the terminal. For debit card surcharge not allowed compliance, the POS must identify the actual card product before applying a fee, automatically exclude debit and applicable prepaid cards, and enforce the same product-level logic for dipped, tapped, keyed, and stored-card transactions.
The most important operational rule is simple: determine what the card is before deciding whether it can be surcharged. A debit card can use different authentication or routing methods, but those processing choices do not turn it into a credit card.
| Card Type | Debit Card Surcharge Rules | POS Compliance Control | Common Failure |
| Consumer credit | Potentially surcharge-eligible under applicable rules | Evaluate network, program, and jurisdiction rules | Incorrect surcharge amount |
| Debit | Surcharge not permitted under applicable Visa/Mastercard credit-surcharge programs | Automatically suppress surcharge | Treat “run as credit” as credit |
| Network prepaid | Excluded under applicable Visa/Mastercard credit-surcharge programs | Identify prepaid funding type and suppress fee | Misclassified BIN/product |
| Closed-loop gift/stored value | Depends on specific program | Identify the actual product/program | Assume all stored value is debit |
| Commercial credit | Potentially eligible subject to rules | Apply valid credit-product logic | Incorrect product mapping |
Debit Card Surcharge Rules: Why Debit Cannot Be Treated Like Credit
Debit card surcharge rules are based on the underlying payment product—not the button the customer presses or the network path used to process the transaction.
Visa and Mastercard U.S. credit-card surcharge programs distinguish eligible credit-card transactions from debit and applicable prepaid transactions. That means a merchant cannot determine surcharge eligibility simply by asking whether a transaction was processed “as credit.”
For debit card surcharge not allowed compliance, keep three concepts separate:
Card product
The actual funding product: credit, debit, prepaid, commercial credit, or another payment type.
Authentication or routing method
How the payment is processed: PIN, no PIN, signature, contactless, chip, keyed entry, or another transaction path.
Surcharge eligibility
Whether the product is eligible under the applicable card-network, processor, merchant-program, and state rules.
Mastercard states directly that its U.S. surcharge permission applies to Mastercard credit cards and that surcharge fees are not allowed on Debit Mastercard or Mastercard prepaid cards. That product-level distinction is why a POS cannot use the presence or absence of a PIN as its surcharge test.
The distinction matters because a debit card run as credit remains a debit card.
Where Durbin Fits Into Debit Card Surcharge Rules
The federal framework is broader than surcharge policy. The Federal Reserve describes Regulation II as the regulation governing debit-card interchange fees and routing, including restrictions on network exclusivity and debit-routing limitations.
The Durbin Amendment is frequently cited when discussing debit card surcharge rules, but it should not be described as the complete source of the debit surcharge prohibition.
Regulation II establishes federal requirements concerning debit-card interchange and routing. It helps define the regulatory separation between debit and credit, but merchants still need to follow the applicable card-network surcharge rules and their acquirer or processor program requirements.
For accurate debit card surcharge not allowed compliance, think of the rule stack this way:
- Federal debit regulation helps define the debit-payment framework.
- Card-network rules determine how network surcharge programs operate.
- State law may add pricing or disclosure requirements.
- Acquirers and processors may impose additional program controls.
- The POS must translate those requirements into transaction-level logic.
That is more accurate than the shorthand statement “Durbin prohibits debit surcharges.”
Signature Debit Is Still Debit Under Debit Card Surcharge Rules
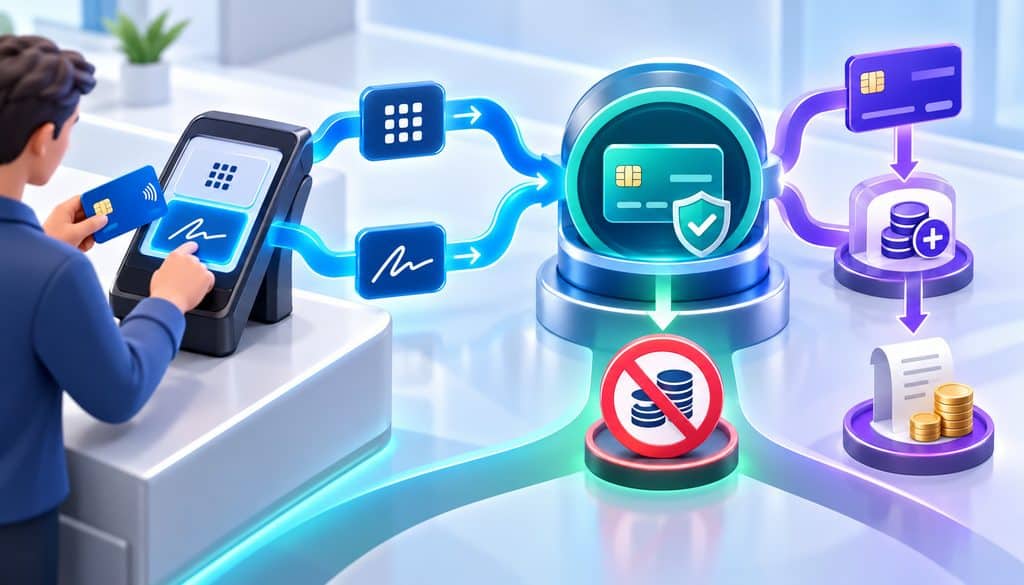
One of the most common debit surcharge compliance mistakes occurs when a customer inserts or taps a debit card and then chooses “credit.”
The transaction might:
- avoid PIN authentication;
- follow another enabled routing path;
- use signature or no-signature processing; or
- appear in the POS differently from a PIN-debit transaction.
None of those changes convert the underlying debit product into a credit card.
Therefore, debit card surcharge rules must follow product classification, not authentication choice.
A surcharge engine should never use these questions as its main test:
- Was a PIN entered?
- Did the customer press “credit”?
- Was the transaction signature-based?
- Did the transaction travel over a network that also processes credit cards?
A merchant may pay the same advertised rate for several card types under a bundled plan even though the underlying transaction economics differ. That distinction becomes easier to see when comparing flat-rate pricing with transaction-specific processing costs, but pricing structure still does not change the debit card surcharge rules.
Instead, the system should ask:
What is the underlying card product, and is that product surcharge-eligible under the merchant’s current program?
Prepaid Cards and Debit Surcharge Compliance
Prepaid-card treatment is another area where debit card surcharge rules need careful implementation.
Visa and Mastercard exclude their applicable prepaid products from their U.S. credit-card surcharge programs. But merchants should not assume that every product commonly described as “prepaid,” “gift,” or “stored value” is technically identical.
The safest POS design classifies the actual product before determining surcharge eligibility.
| Product Type | Surcharge Treatment | Compliance Control |
| Network-branded prepaid debit | Suppress applicable credit-card surcharge | Product/funding classification |
| General-purpose reloadable prepaid | Do not treat as ordinary credit | Processor-supported metadata |
| Payroll/payment card | Determine actual program/product type | Do not infer from appearance |
| Network-branded prepaid gift card | Apply relevant prepaid exclusion | Product mapping |
| Merchant-issued closed-loop gift card | Follow its specific program | Do not invent credit-card rules |
| Unknown stored-value product | Do not default to eligible credit | Fail-safe classification |
For debit card surcharge not allowed compliance, unknown or ambiguous products should not automatically fall into the surcharge-eligible bucket.
How POS Systems Enforce Debit Card Surcharge Rules
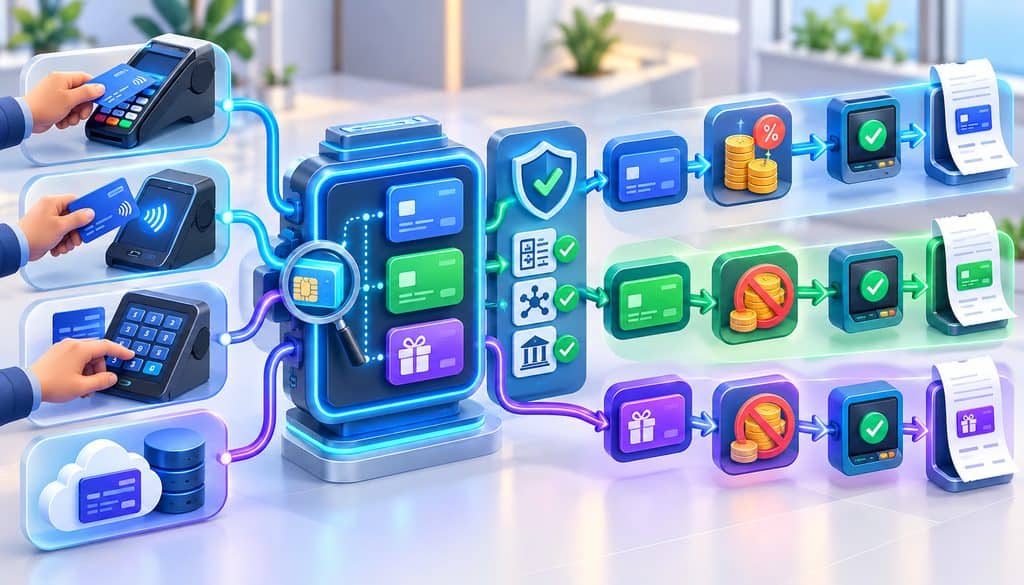
Modern surcharge compliance depends on card-product identification.
A properly integrated payment stack may use BIN/IIN range information together with processor, acquirer, gateway, issuer, and network product metadata to determine whether a credential represents:
- consumer credit;
- commercial credit;
- debit;
- prepaid;
- another payment product.
The important point is that BIN lookup credit vs debit identification should support the surcharge decision before the fee is finalized.
The same product classification used for surcharge decisions also helps explain how different card types affect transaction costs. Debit, basic consumer credit, rewards, and commercial cards can produce different processing costs, but those economics do not determine whether a particular transaction is surcharge-eligible.
Debit Card Surcharge Not Allowed Compliance: What BIN Detection Should Do
A compliant decision path should work in this order:
- Read, receive, or retrieve the payment credential.
- Send the appropriate information to the processor or gateway.
- Determine the card’s current funding/product type.
- Check whether the product is debit, prepaid, or eligible credit.
- If debit or excluded prepaid, set the surcharge to zero.
- If eligible credit, evaluate applicable network, processor, and jurisdiction rules.
- Display the permitted surcharge and final total before completion.
- Authorize the transaction.
- Generate a receipt based on the actual surcharge result.
- Record product classification and surcharge outcome for audit purposes.
This sequence is the practical foundation of debit card surcharge not allowed compliance because the surcharge decision occurs before authorization rather than being attached indiscriminately to every card transaction.
Surcharge POS Configuration for Debit Card Surcharge Compliance
A surcharge feature is not compliant merely because the POS contains an on/off surcharge setting.
The system needs conditional rules.
| POS Control | Required Behavior | Debit Surcharge Risk |
| Card-product engine | Distinguish credit, debit, and prepaid | Debit classified as credit |
| Automatic debit exclusion | Set surcharge to zero | Generic fee reaches every card |
| Prepaid exclusion | Apply relevant network treatment | Prepaid treated as credit |
| State/jurisdiction logic | Apply applicable legal requirements | Same configuration used everywhere |
| Pre-payment display | Show valid fee before payment completion | Surprise surcharge |
| Receipt logic | Print surcharge only when actually applied | Debit receipt shows fee |
| Keyed-payment control | Use same product rules | Every keyed transaction surcharged |
| Stored-card control | Reevaluate supported product metadata | Historical credit flag reused |
| Fail-safe logic | Suppress fee when eligibility is unknown | Unknown defaults to credit |
| Multi-location configuration | Verify every MID/device/location | Some stores use outdated rules |
A strong surcharge POS configuration therefore separates product identification from fee calculation.
The Manual-Entry Gap in Debit Card Surcharge Rules
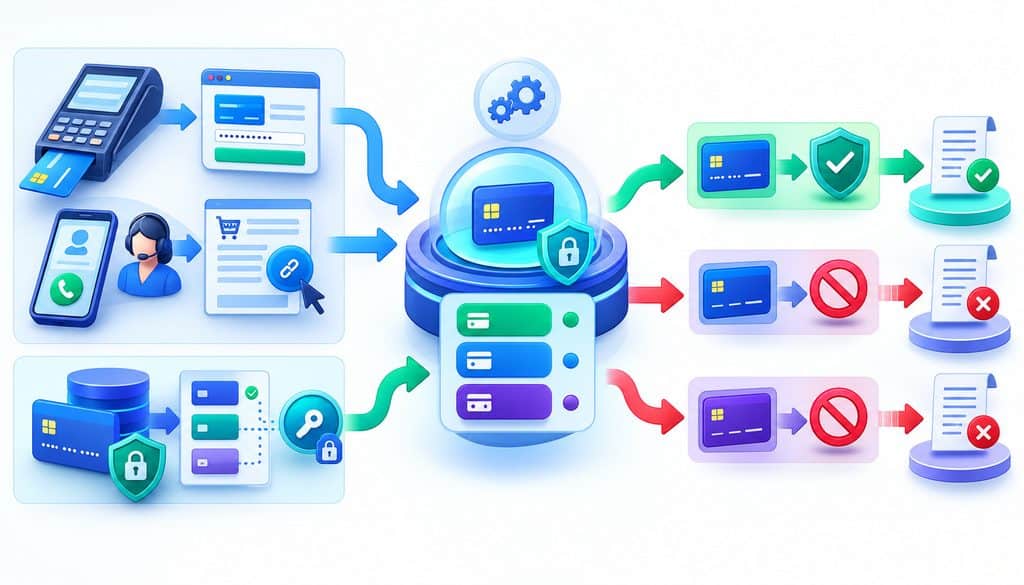
Keyed transactions are particularly important because businesses sometimes configure virtual terminals separately from their retail POS.
A debit card does not become surcharge-eligible because an employee manually types the PAN into a virtual terminal.
The same debit card surcharge rules should apply when:
- a card is manually keyed;
- a customer pays by telephone;
- a payment is entered into a virtual terminal;
- an invoice directs a customer to a payment page;
- a stored token is retrieved for billing.
A properly integrated payment application should still obtain the product classification from processor-supported data.
The employee should not be required to ask, “Is this debit or credit?” and then manually decide whether to add the fee.
Card-on-File Debit Card Surcharge Rules
Stored credentials create another compliance risk because developers may save the original product classification indefinitely.
For example, a stored credential may originally represent an eligible credit card. Later:
- the card may be replaced;
- the underlying account may change;
- an updater service may refresh credentials;
- the token mapping may change; or
- the gateway’s product metadata may be updated.
For debit card surcharge not allowed compliance, the safest approach is to use current processor-supported product information wherever the payment stack makes it available rather than assuming an old credit=true value remains permanently correct.
What Happens When Card-Product Detection Fails?
Debit card surcharge rules should be implemented defensively.
When the application cannot determine whether a product is eligible, a compliance-oriented system should generally:
- suppress the surcharge;
- record the classification error;
- preserve the processor response;
- alert the appropriate administrator; and
- investigate the affected integration.
This is a prudent implementation control rather than a claim that every network mandates identical error-handling logic.
The dangerous design is:
Unknown card → assume credit → surcharge.
That fail-open approach can turn a single BIN or metadata problem into repeated debit-card surcharge errors.
Receipt Rules for Debit Card Surcharge Compliance
Receipt logic must follow the actual transaction result.
If an eligible credit transaction is surcharged under the applicable rules, the receipt needs to reflect the surcharge as required. If the transaction is debit or excluded prepaid, the POS should not print a surcharge amount that was never validly applicable.
| Receipt Item | Eligible Credit | Debit/Prepaid |
| Surcharge calculation | If permitted | $0 |
| Surcharge line | When required/applicable | No debit surcharge line |
| Final total | Match authorization | Match nonsurcharged authorization |
| Transaction record | Preserve surcharge result | Preserve exclusion |
| Refund logic | Handle surcharge consistently | No nonexistent surcharge to refund |
For debit card surcharge rules, the receipt should therefore be downstream of the product-classification engine rather than using a generic “card fee” template.
How to Test Debit Card Surcharge Rules This Week
Every merchant running a surcharge program should test at least one debit path and one eligible credit path.
Test 1 — Debit Card
Use an authorized merchant-owned debit card or approved test credential.
Confirm:
- no surcharge appears before authorization;
- no surcharge appears on the receipt;
- the final authorized total excludes a card surcharge;
- the transaction record identifies the product appropriately.
Test 2 — Eligible Credit Card
Confirm:
- a surcharge appears only if permitted;
- the amount stays within current applicable rules;
- the customer sees it before completion;
- the receipt reflects the actual fee.
Test 3 — Keyed Debit Card
If the merchant accepts keyed payments, repeat the test in the virtual terminal.
The expected result remains:
Debit card = no credit-card surcharge.
Test 4 — Stored Credential
For businesses using card-on-file or recurring payments, verify that stored credentials still pass through the appropriate product-identification logic before a surcharge is calculated.
| Test | Correct Result | Debit Card Surcharge Compliance Failure |
| Card-present debit | No surcharge | Fee added |
| Credit | Conditional permitted surcharge | Invalid amount/disclosure |
| Keyed debit | No surcharge | Virtual terminal adds fee |
| Stored-card debit | No surcharge | Old credit classification reused |
Common Debit Card Surcharge Rules Mistakes
| Mistake | Why It Fails | Better Control |
| Treat “run as credit” as a credit card | Routing does not change funding product | Product-level classification |
| Ask cashier to identify debit manually | Human error | Processor metadata |
| Maintain static BIN spreadsheet | Data can become outdated | Maintained product service |
| Apply one generic card fee | Hits ineligible products | Conditional surcharge engine |
| Forget keyed transactions | Alternate channel bypasses rules | Shared classification logic |
| Trust stored token forever | Underlying credential may change | Current product data |
| Surcharge prepaid cards | Conflicts with applicable program rules | Explicit prepaid exclusion |
| Print surcharge on debit receipt | Receipt template ignores eligibility | Conditional receipt logic |
| Add fee after authorization | Transaction totals become inconsistent | Decide before authorization |
| Test only one store | Configurations differ | Location-level validation |
Frequently Asked Questions
Can I surcharge a debit card if the customer chooses “credit”?
No. For Visa, the network expressly says the choice does not change the fact that the cardholder is using a Visa debit card. Mastercard’s U.S. surcharge permission also excludes debit.
What if the card has a Visa or Mastercard logo?
The logo identifies a payment network, not by itself whether the product is credit, debit, or prepaid. Use electronic product classification.
Can I surcharge prepaid cards?
Visa and Mastercard exclude their prepaid products from their U.S. credit-card surcharge programs. Closed-loop gift or stored-value programs should be evaluated under the rules governing those specific products rather than assumed to follow ordinary credit-card surcharge rules.
How does my POS know whether a card is debit?
Typically through processor/acquirer/network product metadata associated with the account range, BIN/IIN, and other product attributes—not from the customer’s terminal-button selection.
Can I ask the customer whether the card is debit or credit?
You can communicate with the customer, but their answer should not be the primary technical eligibility control. The payment platform should classify the credential.
Can I surcharge a keyed debit card?
No under the Visa/Mastercard U.S. credit-surcharge programs discussed here. Manual entry changes the entry method, not the product.
What about card-on-file transactions?
Apply the same product-eligibility decision. Do not assume an old token or customer record permanently proves that the current credential is eligible credit.
Does the surcharge have to appear separately on the receipt?
Visa’s U.S. guidance calls for separate identification of the surcharge amount, while Mastercard requires disclosure of the dollar amount on the transaction receipt. Confirm the current requirements for every network, jurisdiction, and acquirer in your program.
What happens if I accidentally surcharge debit?
Correct the customer impact, preserve the transaction evidence, investigate how the product was classified, correct the POS/gateway configuration, retest, and follow any acquirer remediation instructions.
Is a cash discount the same as a credit-card surcharge?
No. They are distinct pricing constructs. The actual pricing mechanics—not simply the label placed on a fee—determine which rules need to be evaluated.
Build Debit Card Surcharge Compliance Around the Card Product
The core debit card surcharge rules are operationally straightforward: identify the actual payment product before calculating a fee, suppress the surcharge on debit and applicable prepaid products, and apply the same product classification across tap, dip, keyed, virtual-terminal, and stored-card transactions.
For strong debit card surcharge not allowed compliance, merchants should also make receipt templates conditional, fail safely when product classification is unavailable, test both debit and eligible credit transactions, and audit surcharge data across every location and payment channel.
The safest surcharge program does not depend on the cashier, the customer, or the word “credit” on the terminal. It depends on accurate card-product identification and conditional POS logic.